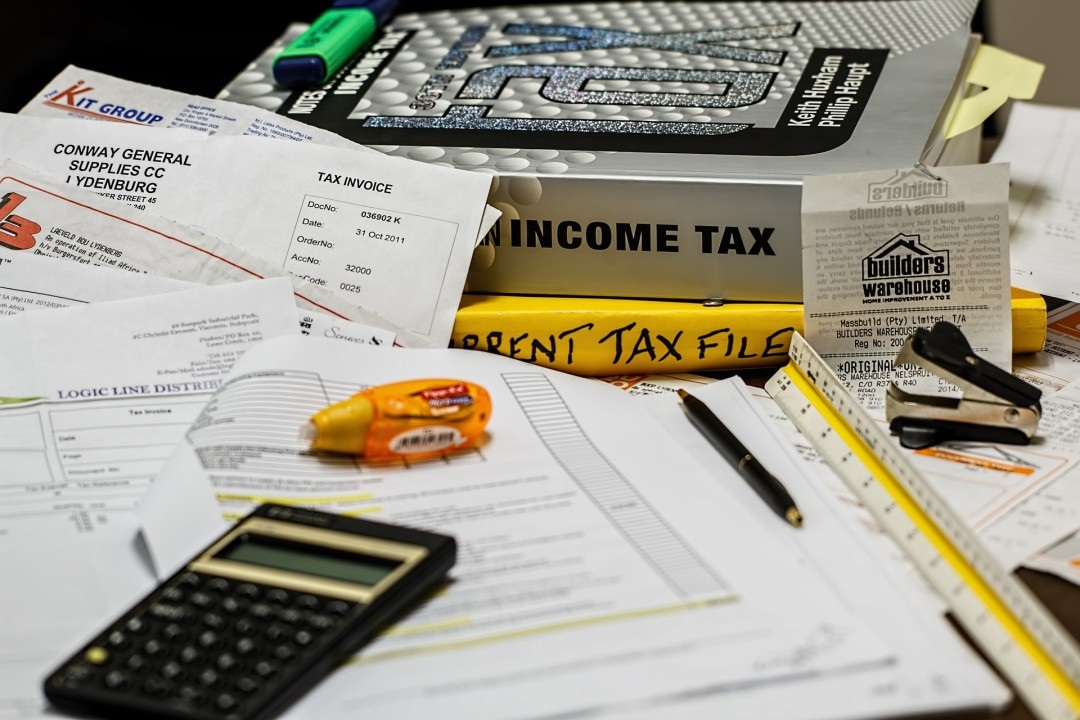
Businesses registered as limited companies in Kenya are subject to corporate income tax on their profits, a different regime from the individual income tax or Turnover Tax that applies to many sole proprietorships. Understanding the basics helps directors avoid costly compliance mistakes.
Corporate tax is charged on taxable profit, which is calculated by starting with accounting profit and then adjusting for items that tax law treats differently from standard accounting, such as certain non-deductible expenses or specific capital allowances on business assets. This means a company's taxable profit can differ meaningfully from the profit shown in its own management accounts.
Companies are generally required to make advance tax payments in installments throughout the year based on estimated annual profit, with a final reconciling payment or refund once the annual return is filed. Underestimating these installments can result in penalties, while significantly overestimating them ties up cash the business could otherwise use.
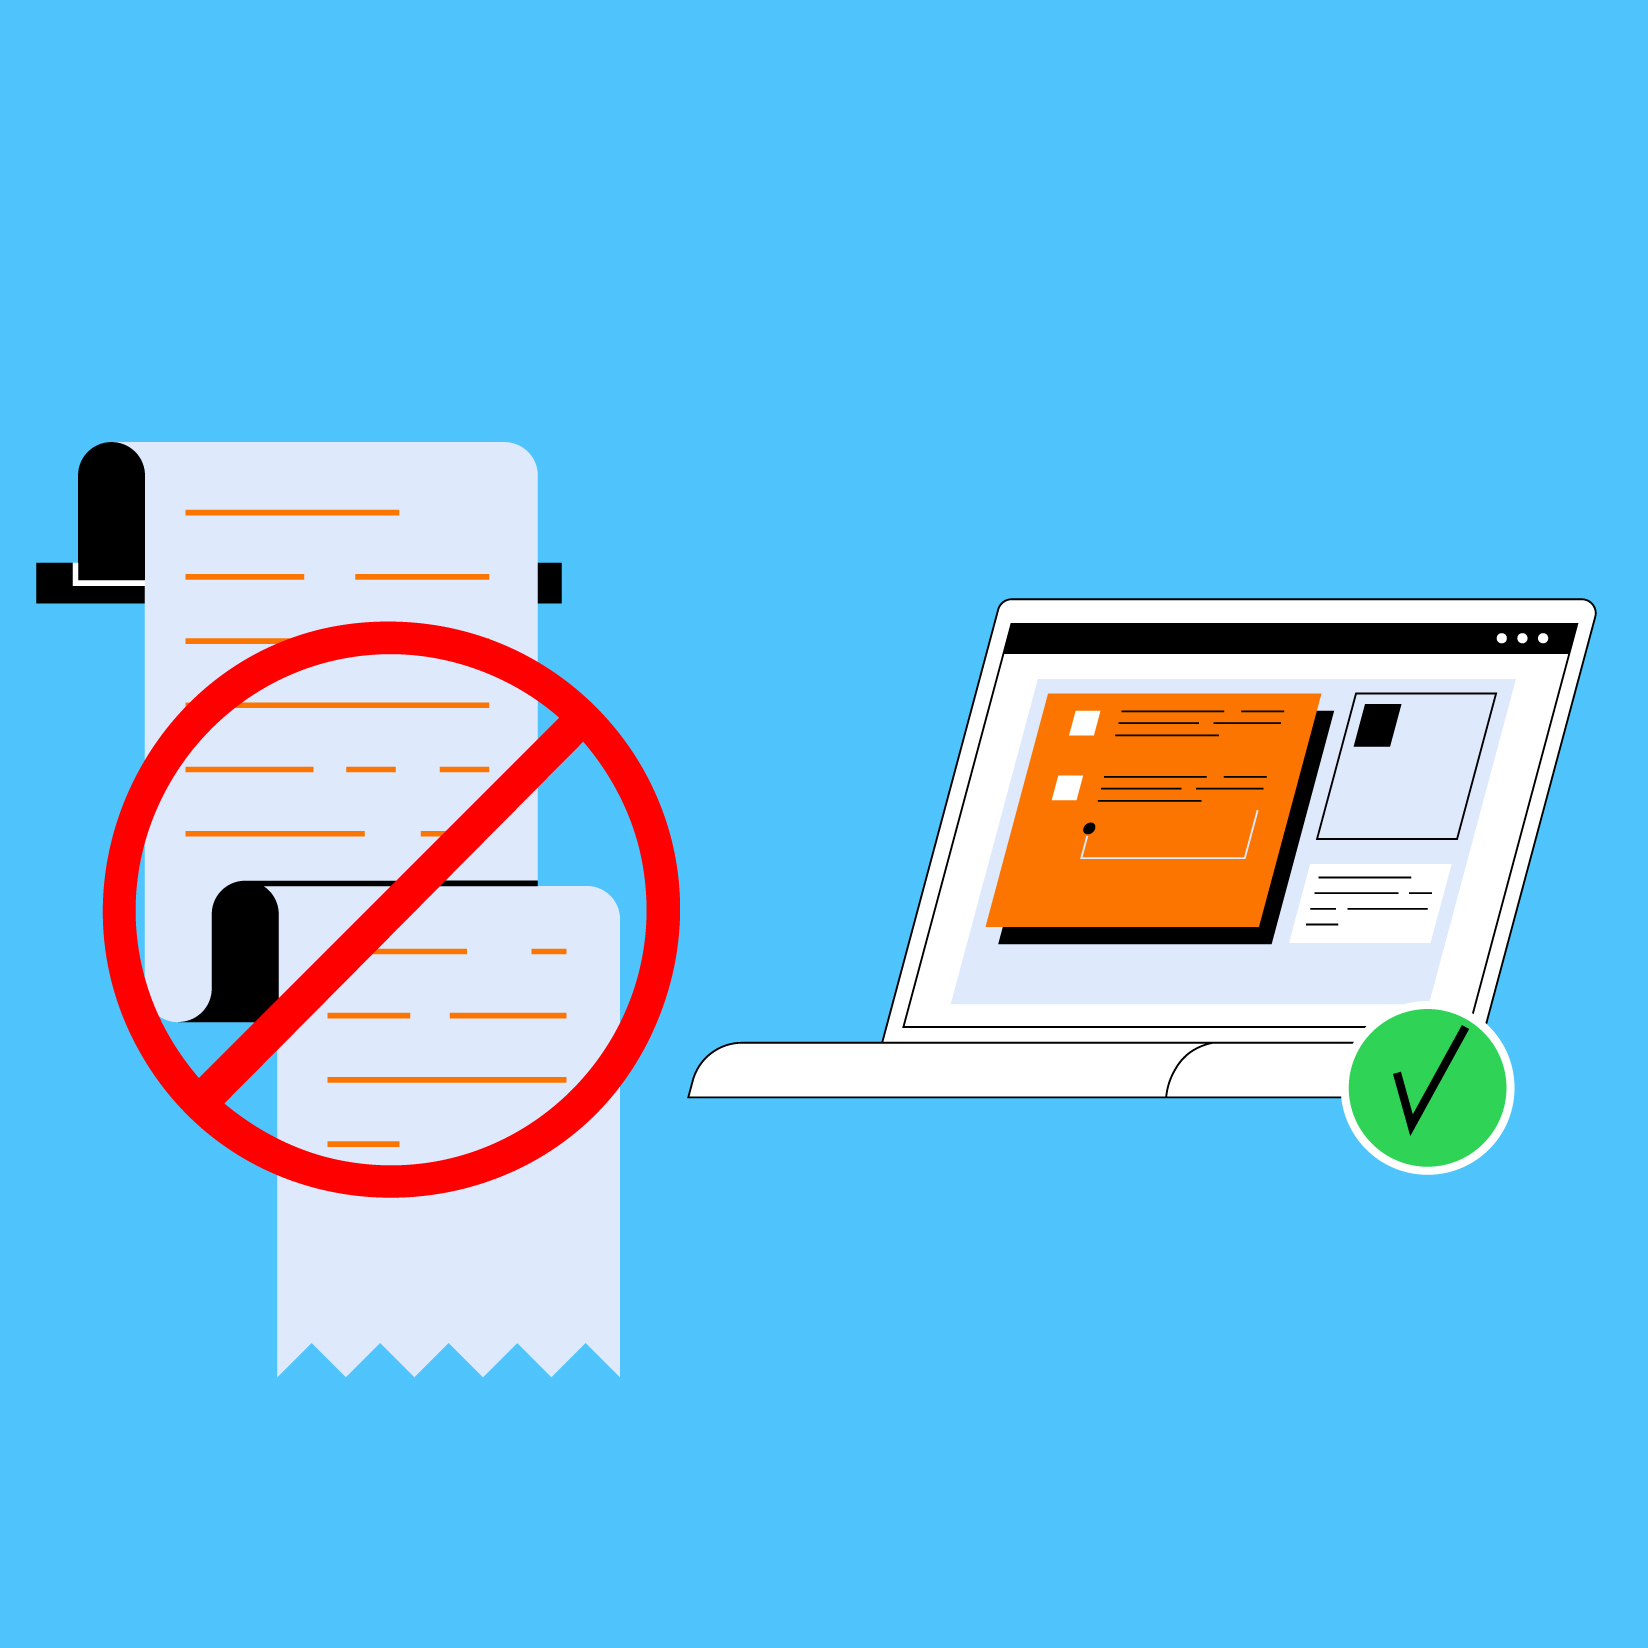
Because corporate tax calculations depend heavily on accurate, well-organized financial records throughout the year, companies benefit from maintaining a clean digital trail of income and expenses. Tools like paperlesskenya.co.ke, used alongside a qualified accountant, make it considerably easier to prepare accurate installment estimates and a defensible annual return.
Company directors should work closely with a qualified accountant when preparing corporate tax computations, since the adjustments between accounting profit and taxable profit involve technical rules that are easy to apply incorrectly without proper training or experience.
Directors should also review corporate tax computations from prior years periodically, since patterns or recurring adjustments often reveal opportunities to plan more efficiently for future periods.
Careful, well-advised corporate tax planning protects company directors from avoidable liabilities and penalties.
This kind of careful planning, sustained consistently, protects both the business and its directors from avoidable financial exposure.
Company directors who plan tax obligations proactively, rather than reactively at filing time, consistently reduce both their stress and their overall compliance costs.
 Paperless