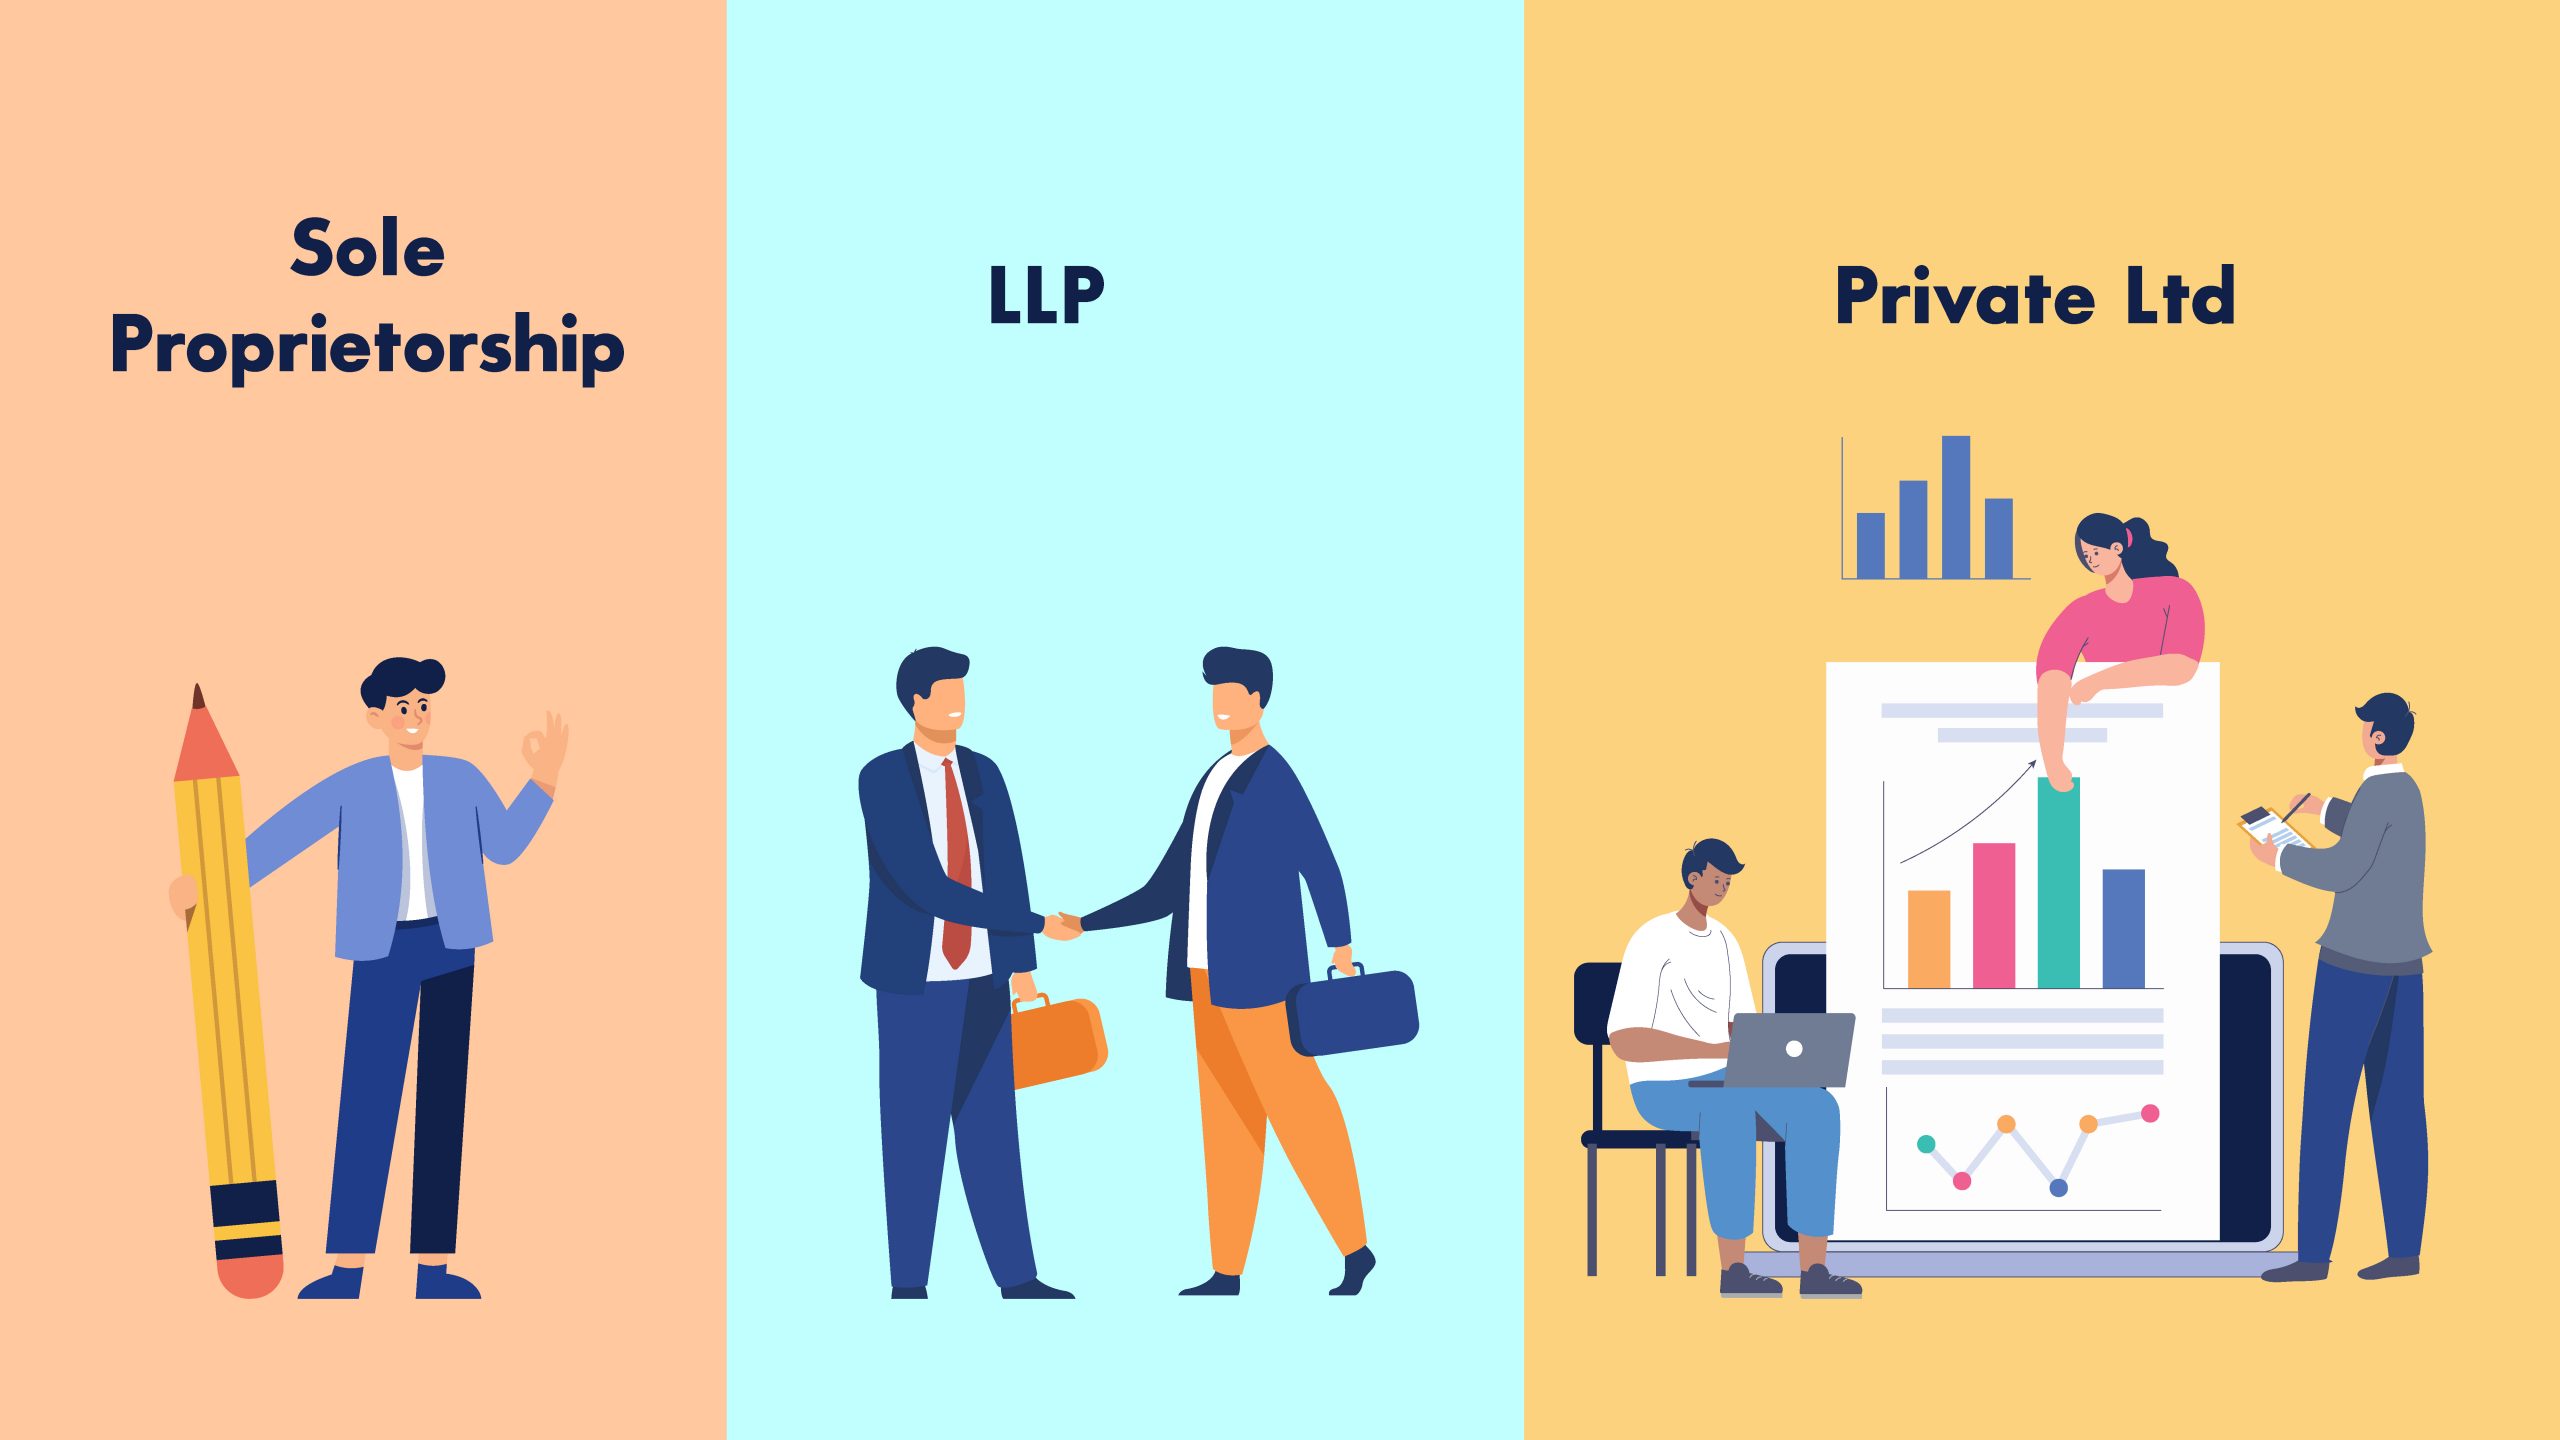
Choosing between operating as a sole proprietor or registering a limited company is one of the earliest and most consequential decisions a Kenyan entrepreneur faces when starting a business.
A sole proprietor has unlimited personal liability for business debts, meaning personal assets can be at risk, while a limited company is a separate legal entity generally limiting shareholder liability to their investment.
A sole proprietor's business income is taxed as part of their individual income tax, while a limited company is taxed separately under corporate tax rules, with different rates and reporting requirements applying.
A limited company faces additional ongoing compliance obligations, including statutory filings and more formal accounting, while a sole proprietorship involves considerably simpler administration.
The right choice depends on your risk exposure, growth ambitions, and whether you plan to bring in investors or pursue significant contracts, and organized records through a service like paperlesskenya.co.ke support either structure equally well.
Neither structure is universally better; the right choice depends entirely on your specific business's risk profile and growth plans.
Not necessarily; a well-designed template in a word processor or spreadsheet is sufficient for many small businesses, though dedicated invoicing tools add convenience as invoice volume grows.
Neither business structure is universally superior; the right choice depends entirely on your specific risk profile and growth ambitions.
Weigh your specific risk exposure and growth plans honestly against the differences outlined above, and consider a brief consultation with an advisor if the right choice still feels unclear.
Neither structure is universally better; the right choice depends entirely on your specific risk tolerance and growth ambitions.
This distinction, understood clearly from the outset, protects you from a decision made hastily without full awareness of its consequences.
 Paperless